Public study · Mauritius · 2026
Institutional Execution Advantage
Mauritius executes what someone else scores
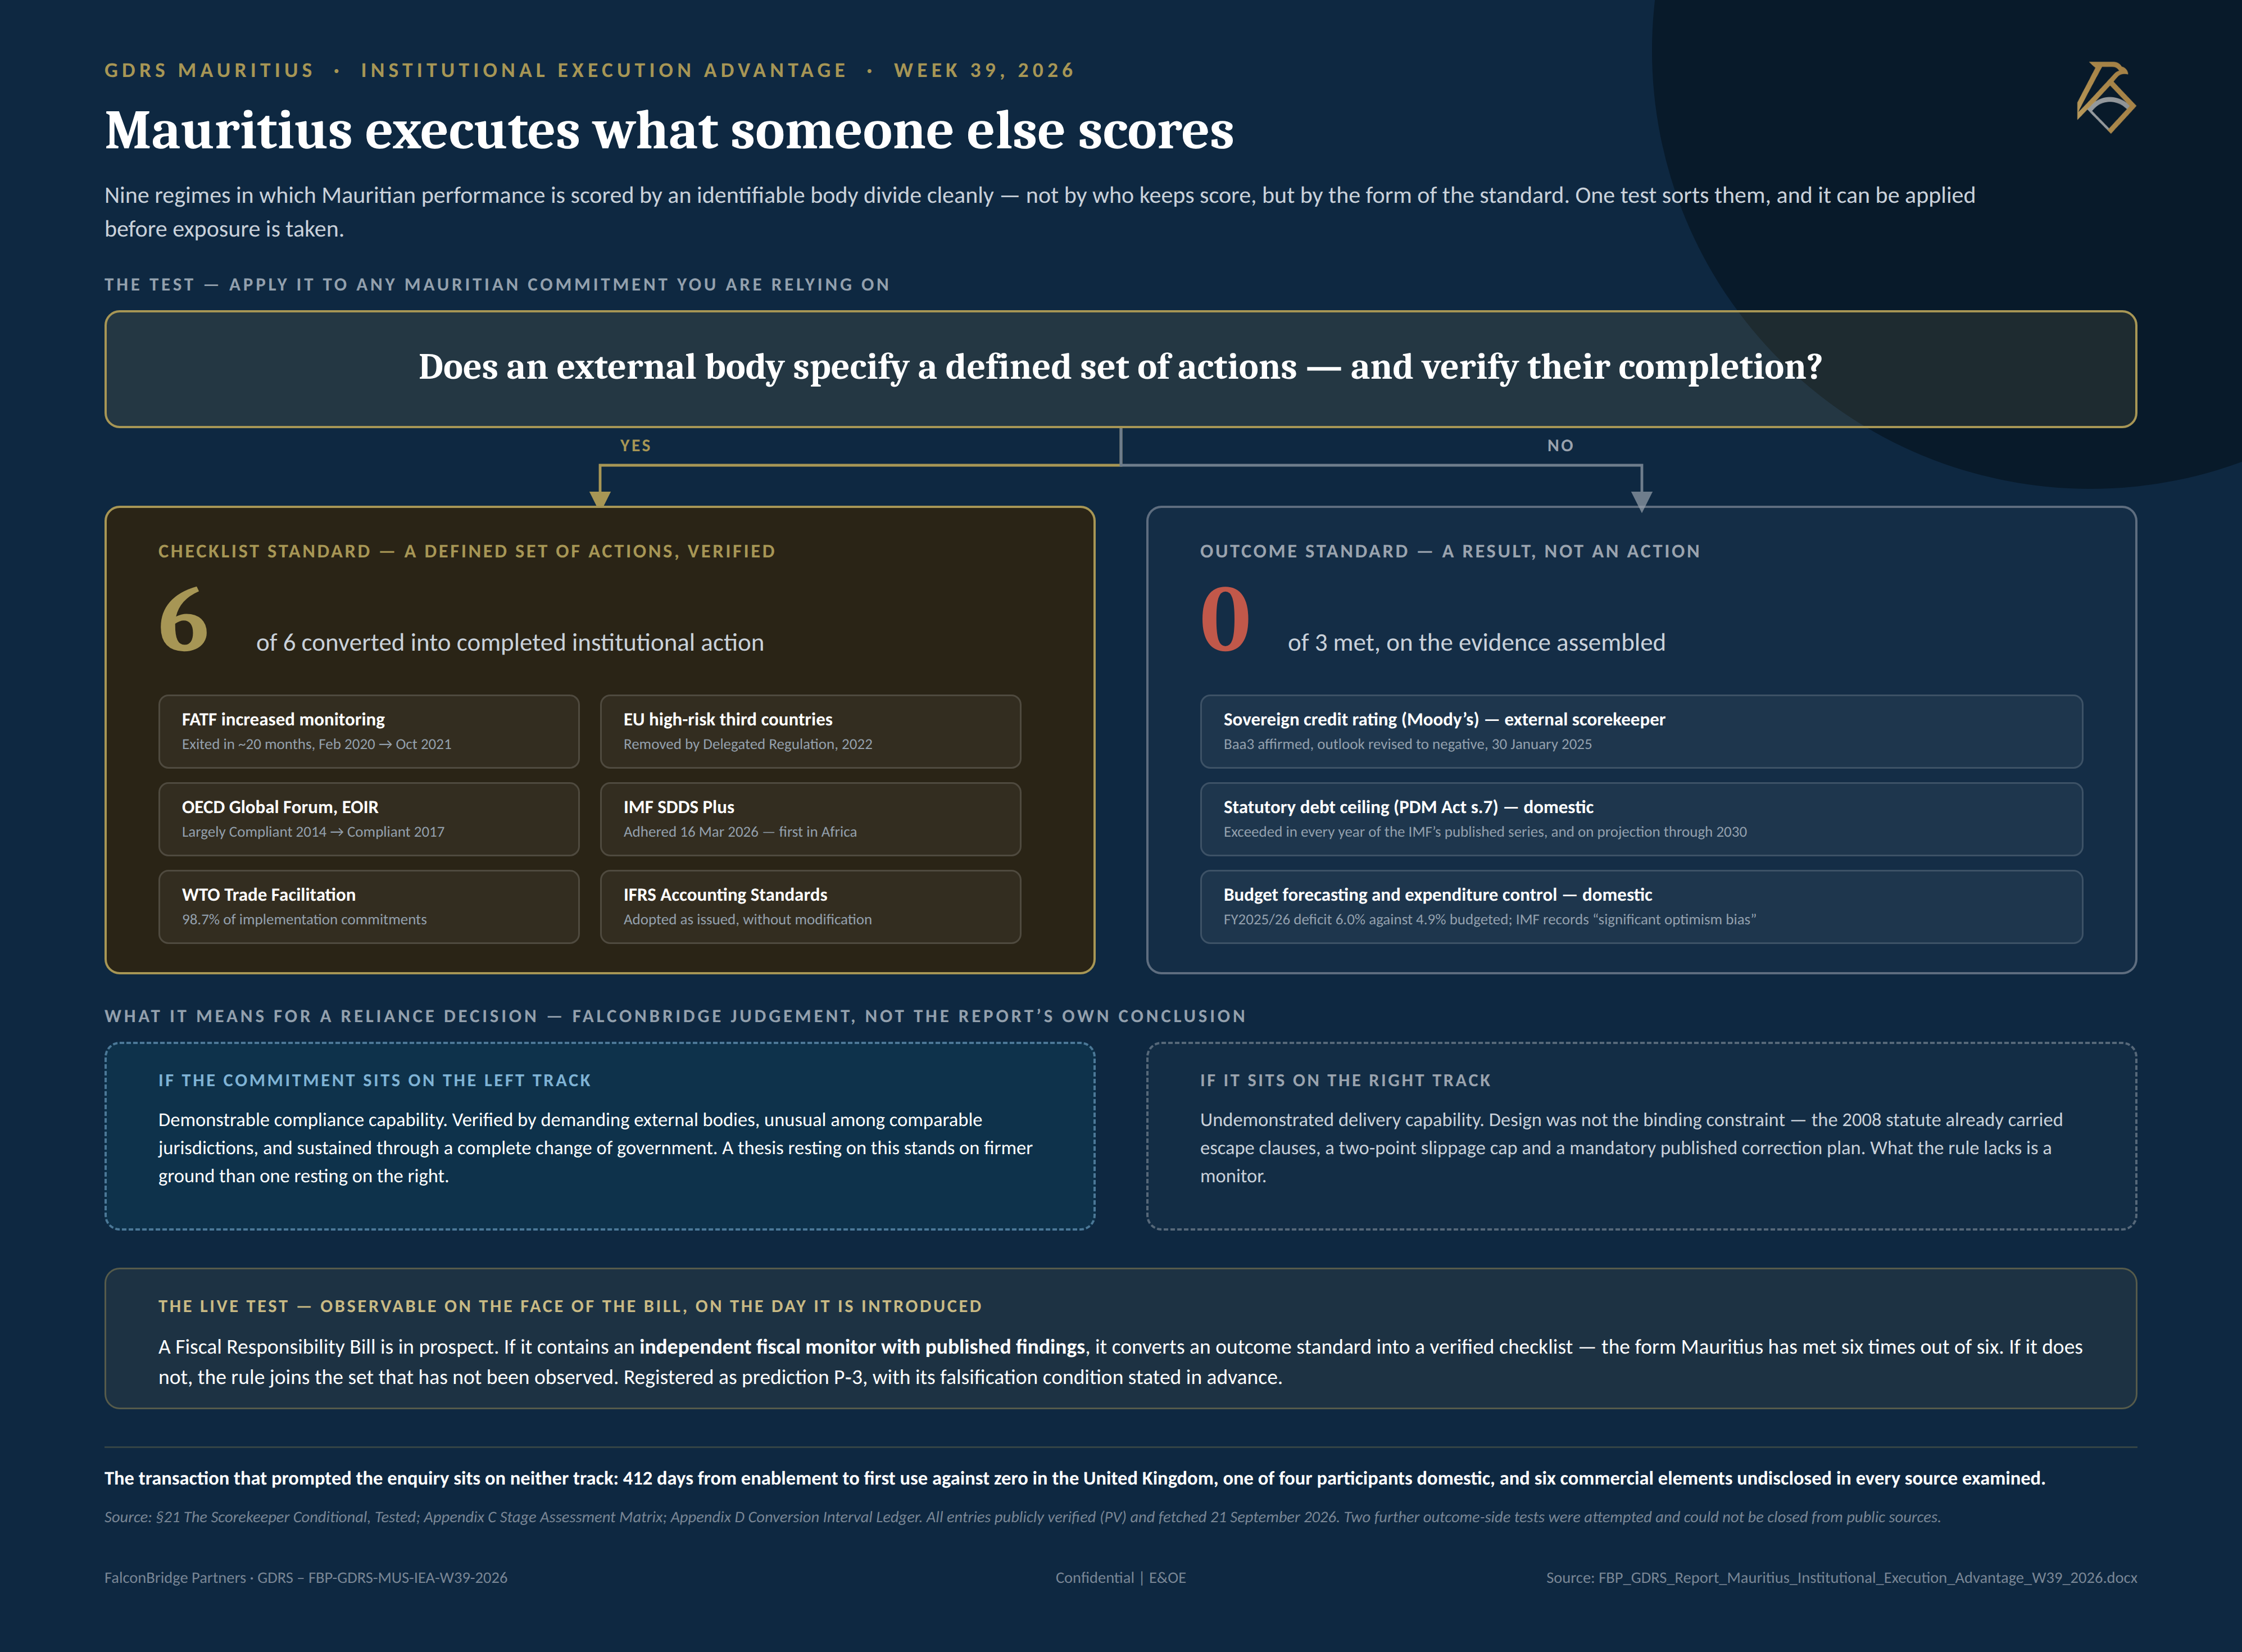
Two developments in the week ending 20 September 2026 — a trade-finance transaction in electronic bills of exchange under Mauritian law, and an IMF mission on Fiscal Responsibility Legislation conducted at the government’s own request — invited a proposition: that Mauritius is converting reform intent into operating capability, and that the conversion is becoming a source of advantage. The study was commissioned to test that proposition rather than to advance it. As a jurisdiction-wide property it does not survive the evidence, and the margin is not narrow. Across nine regimes in which Mauritian performance is scored by an identifiable body, the record divides cleanly and not along the line expected. Six for six where an external body specifies a defined set of actions and verifies their completion; nought for three where performance is measured as an outcome. FATF exit in roughly twenty months, EU delisting, an OECD tax-transparency upgrade to Compliant, IMF SDDS Plus adherence as the first African subscriber, WTO trade facilitation at 98.7 per cent, and IFRS adopted as issued — against a sovereign rating outlook revised to negative, a statutory debt ceiling exceeded in every year of the IMF’s published series, and a FY2025/26 deficit of 6.0 per cent against 4.9 per cent budgeted. What separates the two sets is the form of the standard, not the identity of the scorekeeper. Four of the six regimes that were met carry no identified cost of failure; the one that carries a priced, market-transmitted cost was not met. Nor was design the binding constraint on the fiscal side: the 2008 Public Debt Management Act already contained defined escape clauses, a slippage cap of two percentage points a year, and a mandatory published correction plan. What the existing rule lacks is a monitor. That makes the Fiscal Responsibility Bill now in prospect a live test — if it contains an independent fiscal monitor with published findings it converts an outcome standard into a verified checklist, and on the study’s reading materially raises the probability of behavioural change. The transaction that prompted the enquiry is approximately uninformative about any of this. It is real, competently executed and correctly reported — five electronic bills of exchange created in under thirty minutes on 17 September 2026 — but the interval from enablement to first use was 412 days, against zero days in the United Kingdom, where a clearing bank transacted on the day its Act came into force. One of four named participants is a Mauritian institution; the platform’s reliability was assured not by any Mauritian body but by the ICC Digital Standards Initiative with Canada’s Digital Governance Council, ten months earlier. Against a global base rate of roughly five per cent of bills of lading issued electronically in mid-2024, a single transaction is indistinguishable from the norm. Four matters material to any reliance decision remain open. The Electronic Transactions (Amendment) Act 2026 commences on a date to be fixed by Proclamation, and no proclamation notice was displayed on the responsible regulator’s Acts page 119 days after assent; the in-force enablement reaches bills of exchange only and not the electronic bill of lading; six commercial elements of the September transaction are undisclosed in every source examined; and two Mauritian official bodies publish, as current, a debt ceiling abolished in 2020. Each of these is recorded as not located as at 21 September 2026, never as an assertion that the thing does not exist. A reader could reasonably conclude that the useful question is not whether Mauritius executes, but which of two separable capabilities a given commitment belongs to — one demonstrable, one undemonstrated — and that the classification is answerable from public records before exposure is taken. On the digital-trade side specifically, a counterparty whose capability is built around bills of lading could consider establishing that the enablement reaches its own instrument before relying on it. Figures and findings above are drawn from the source report and are publicly verified (PV) on its own evidence classification, fetched and confirmed on 21 September 2026. The final paragraph is judgement offered for the reader’s own decision; it is not advice, and the source report makes no recommendation to act.. E&OE. All rights reserved.
Six for six, nought for three
Six for six where an external body specifies a defined set of actions and verifies their completion; nought for three where performance is measured as an outcome.
412 days
It is real, competently executed and correctly reported — five electronic bills of exchange created in under thirty minutes on 17 September 2026 — but the interval from enablement to first use was 412 days, against zero days in the United Kingdom, where a clearing bank transacted on the day its Act came into force.
A monitor
What the existing rule lacks is a monitor.
The Weekly Signal behind this study
Mauritius · Week 39, 2026
The complete package
Five elements, tailored to the question and to how readers will use the work
Tell us who is reading and the pack is emailed to you straight away. The package is released under a Type-1 licence for the requester’s own use. Public access does not transfer ownership.
A conversation about your decision
What needs to be understood
before your next decision?
Bring the proposition, question or direction you are working on. Together, we can define the support it requires.
Start a conversation